


Are IC Markets UK Clients Covered by the FSCS or Financial Ombudsman?
No. UK clients of IC Markets get neither FSCS compensation nor access to the Financial Ombudsman. Here is what IC offers instead, and why the £120,000 figure you see online is wrong.
 WriterAbir KhanWriterWrites the guides · checks every figure against primary sources View profileAbout Abir →

 Market analysisTanbir Habib RiyadForex & Crypto AnalystForex and crypto analyst · technical and fundamental analysis View profileAbout Tanbir →

 Fact-checking & riskJannatul FerdaushFact-Checker & Risk AnalystFact-checks every figure · risk analysis · Applied Statistics, University of Dhaka View profileAbout Jannatul →

 Trading reviewJowel RanaCo-Founder & Forex TraderCo-founder · forex trader · reviews guides from a trader's view View profileAbout Jowel →

 Final approvalRanjan NiskrityFounder, Owner & Forex TraderFounder and owner · forex trader · signs off every guide View profileAbout Ranjan →

No. If you live in the UK and trade with IC Markets (now trading as IC), you are not covered by the Financial Services Compensation Scheme and you cannot take a complaint to the Financial Ombudsman Service. Both schemes only protect customers of firms authorised by the FCA, and no IC company holds UK authorisation. UK residents are onboarded in practice by Raw Trading Ltd in the Seychelles, and the FCA’s own Warning List entry against IC Markets Global says in terms that UK customers won’t have Ombudsman access or FSCS protection. What IC offers instead is a private insurance policy and a complaints route that ends in the Seychelles courts.
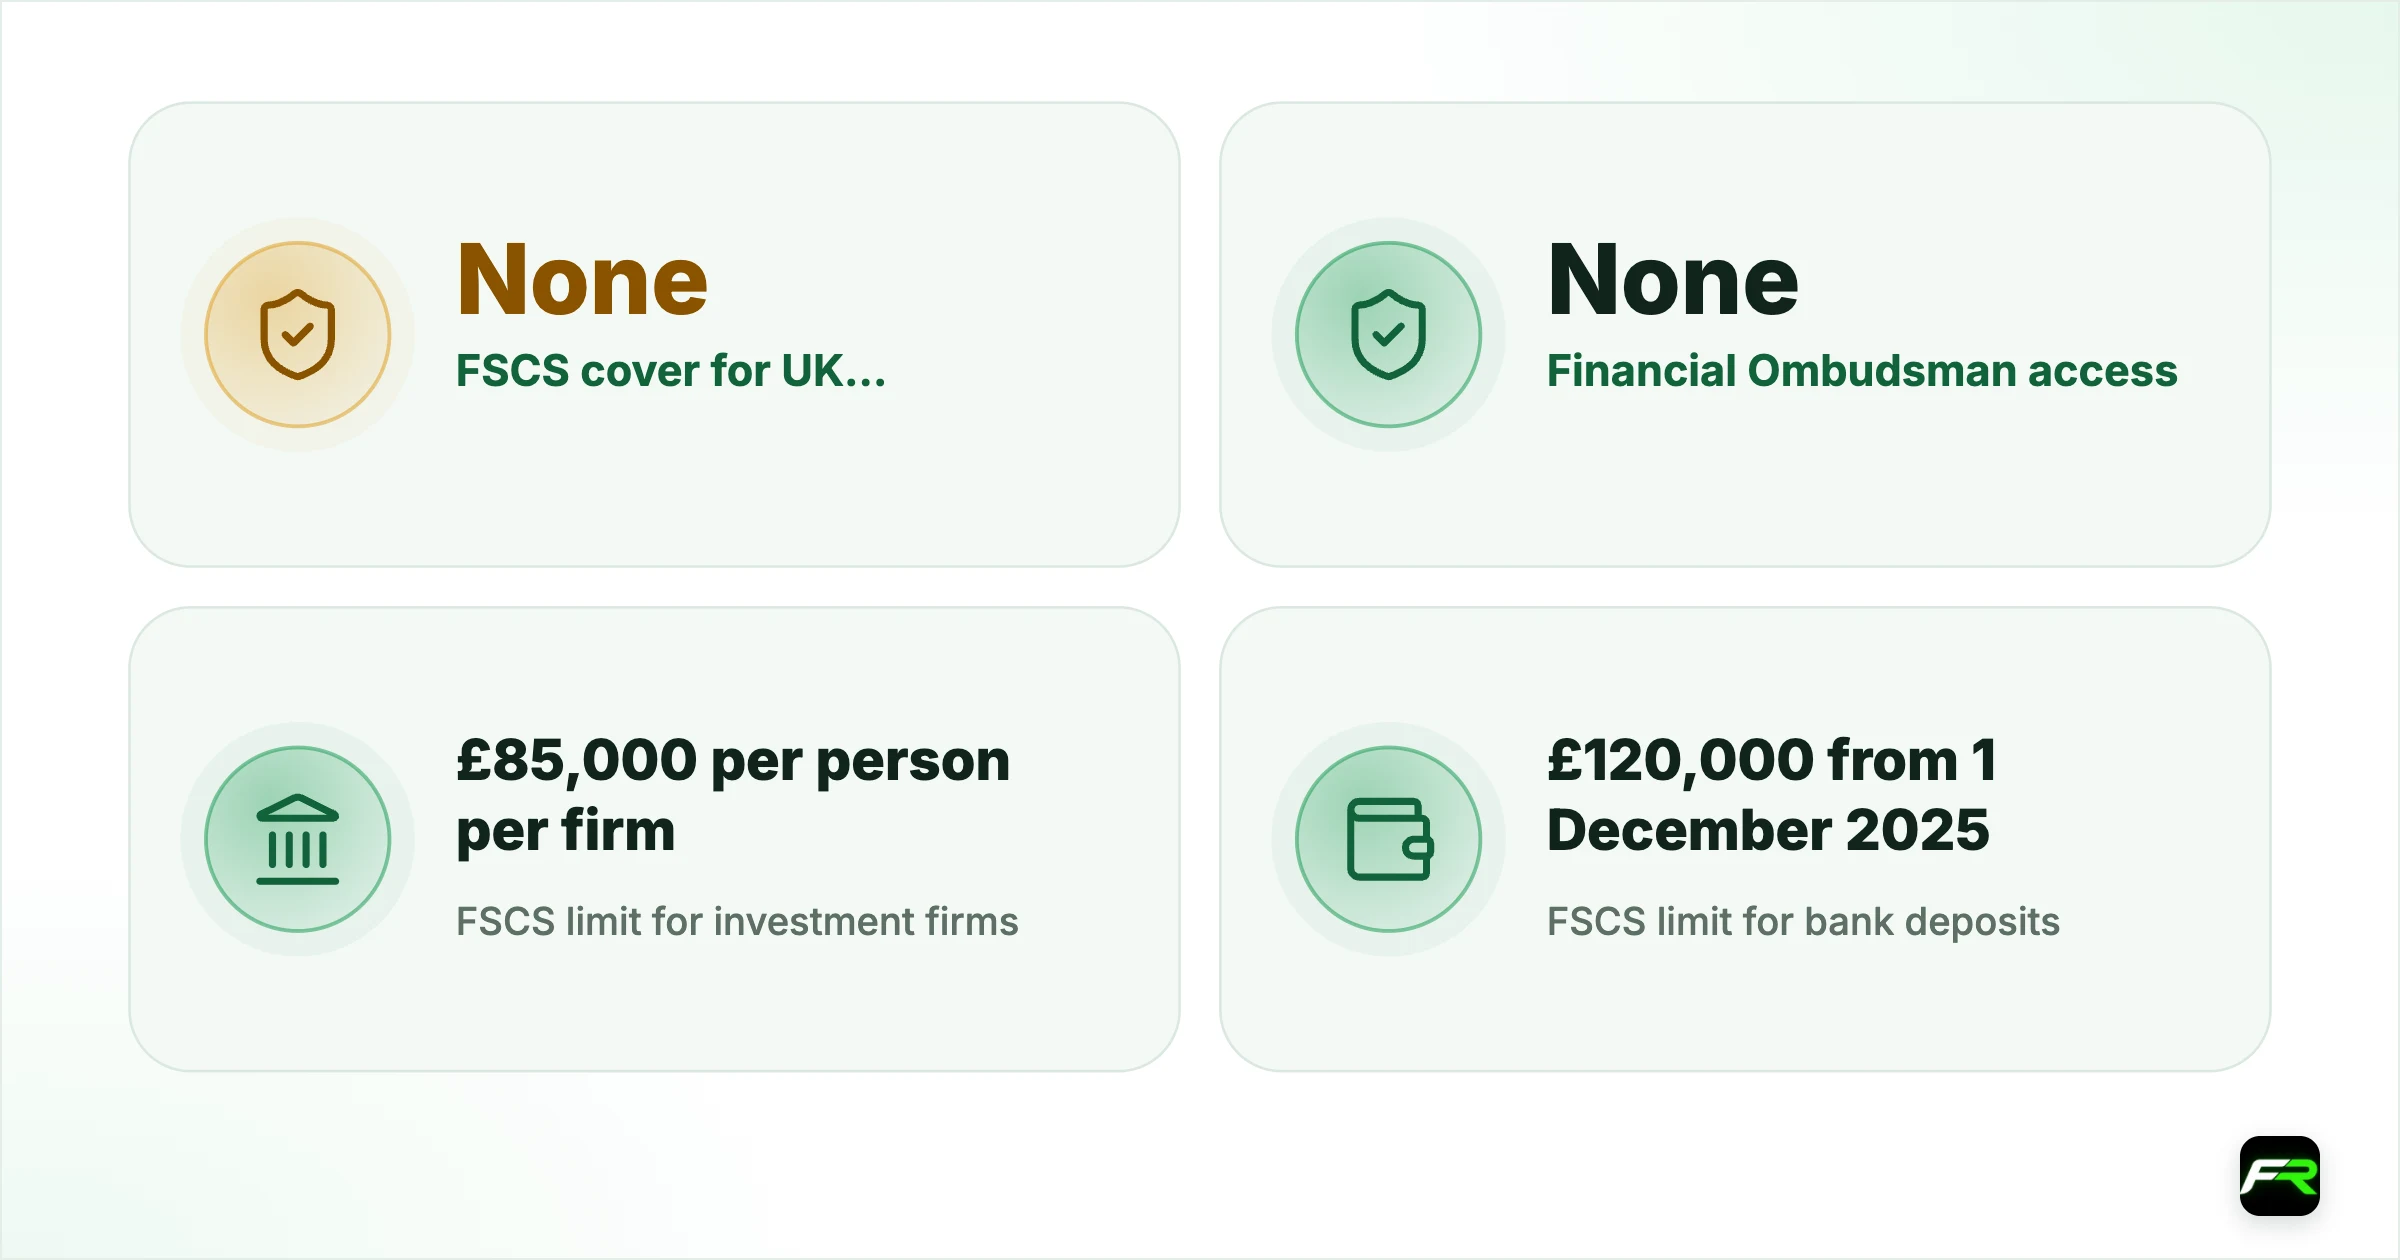
Plenty of comparison pages muddle this, often quoting a £120,000 FSCS limit that has nothing to do with brokers. Below we set out the real UK limits, what IC provides in their place, how a dispute would work in practice, and how to size your balance given the gap.
| FSCS cover for UK IC clients | None |
|---|---|
| Financial Ombudsman access | None |
| FSCS limit for investment firms | £85,000 per person per firm (FCA-authorised firms only) |
| FSCS limit for bank deposits | £120,000 from 1 December 2025 (not relevant to brokers) |
| Ombudsman award limit | £455,000 for complaints referred from 1 April 2026 about acts from 1 April 2019 |
| What IC offers instead | Client money insurance, stated as up to USD 1,000,000, for Raw Trading Ltd insolvency |
Why neither UK scheme applies
The FSCS is the UK’s compensation fund of last resort. It pays out when an FCA-authorised firm fails and cannot return money or assets it was holding for you. The Financial Ombudsman is a free, independent service that settles complaints between consumers and firms within its jurisdiction, and its decisions bind the firm if you accept them. Both schemes hang off UK authorisation. A firm outside the FCA’s perimeter isn’t a participant in the FSCS and isn’t subject to the Ombudsman’s compulsory jurisdiction.
IC has no UK company and no FCA permission. Its Cyprus company, IC Markets (EU) Ltd, once held a passport and then a temporary permission under FRN 827935, but that record is historical and the Temporary Permissions Regime closed on 30 December 2023. The FCA warning on IC Markets Global, updated on 10 August 2026 to name ic.com, spells out the consequence: no Ombudsman if you want to complain, and no FSCS, so you are unlikely to get money back if the firm goes out of business. Our piece on IC Markets and the FCA covers the three FCA records in detail.
The £85,000 and £120,000 confusion
Search for "IC Markets FSCS" and you will find pages promising UK clients protection of up to £120,000. That claim is wrong twice over. The £120,000 figure is the FSCS limit for money held in UK banks, building societies and credit unions, raised from £85,000 on 1 December 2025. It has never applied to investment firms. For a failed broker, platform or CFD provider, FSCS investment protection stays at £85,000 per person per firm, for firms that failed after 1 April 2019.
And even the correct £85,000 figure only applies to FCA-authorised firms. A UK resident at IC gets neither amount. It is also worth being clear about what the FSCS does for customers of an authorised broker: it covers a shortfall in client money or assets when a firm collapses, not trading losses. Losing £5,000 on a GBP/JPY trade is never an FSCS matter at any broker.
| Scheme or cover | Limit | Who it protects | UK clients of IC? |
|---|---|---|---|
| FSCS, bank deposits | £120,000 per person per bank (from 1 Dec 2025) | Savers at UK-authorised banks | Not relevant |
| FSCS, investment firms | £85,000 per person per firm | Clients of FCA-authorised firms that fail | No |
| Financial Ombudsman | Awards up to £455,000 (acts from 1 Apr 2019, referred from 1 Apr 2026) | Complainants against firms in its jurisdiction | No |
| CySEC Investor Compensation Fund | Lower of 90% of the covered claim or EUR 20,000 | Clients of IC Markets (EU) Ltd | No, the EU entity excludes UK residents |
| IC client money insurance | Stated as up to USD 1,000,000 "for all claimants" | IC clients of Raw Trading Ltd, on its insolvency | Yes, in practice |
You can check the FSCS limits on the FSCS website and the Ombudsman’s award limits on the Financial Ombudsman’s site. For how the schemes work at UK brokers generally, see FSCS protection at forex brokers.
What IC offers instead
IC points UK and other offshore clients to three things. Each is real, and each is weaker than it may sound.
Client money insurance
IC’s insurance page says the policy "will cover up to US$1,000,000 for all claimants", is "available to all the IC clients of Raw Trading Ltd", and "will be triggered only in the unlikely event of Raw Trading Ltd’s insolvency". It covers the available balance and open CFD positions. The page gives a policy number but does not name the insurer, and it publishes no claims procedure or exclusions.
Read literally, "up to US$1,000,000 for all claimants" describes a limit shared across everyone who claims, not USD 1 million each. IC does not spell that out, so ask its support team for the policy wording in writing if the point matters to you. Either way, this is a private commercial policy. There is no statutory scheme behind it, no UK body to appeal to, and a claim would sit inside a Seychelles insolvency.
Complaints and the Seychelles courts
A dispute starts with IC’s internal complaints process. Clause 28 of the Raw Trading Ltd terms puts the agreement under Seychelles law and courts. Beyond the firm, your options are to raise the matter with the Seychelles Financial Services Authority, which licenses Raw Trading Ltd under SD018, or to bring a claim in the Seychelles. Neither is free, fast or familiar in the way the Ombudsman is for a UK consumer.
No negative balance guarantee
UK CASS rules, which force authorised firms to keep client money in segregated accounts out of reach of creditors, are policed by the FCA and don’t apply to an offshore company. IC also offers no guaranteed negative balance protection for these accounts: its Help Centre says that if you lose more than your balance "you will bear the negative consequences". FCA rules cap a retail client’s loss at the funds in the account, as our explainer on margin close-out and negative balance protection shows.
What about CySEC’s Investor Compensation Fund?
Some pages note that IC Markets (EU) Ltd is a member of Cyprus’s Investor Compensation Fund and imply that UK traders benefit. They don’t. The ICF covers clients of the Cyprus company, paying the lower of 90% of the covered claim or EUR 20,000 if that firm fails. IC’s EU website states that the information on it is "not intended for residents of Brazil, Belgium, the United Kingdom or the United States", so a UK resident signing up today does not become a client of that company.
Someone who opened an account with the EU entity years ago, before the temporary permission ended, should check their paperwork. For everyone else the ICF is irrelevant. Our article on which IC company takes UK residents explains how to find the contracting party on your agreement.
How a dispute would compare
Picture a common complaint: a stop loss filled well away from your level around a news spike, and you believe the firm owes you £1,200. At an FCA-authorised broker, you complain in writing, the firm has eight weeks to respond, and if you disagree with its final response you have six months to take it to the Ombudsman at no cost. An adjudicator reviews the evidence and the firm must follow any award you accept.
At IC, you complain in writing and IC decides. If you disagree, there is no free independent referee. A complaint to the Seychelles FSA is possible, but a regulator is not an ombudsman and does not usually settle individual money claims. A court claim in the Seychelles for £1,200 would cost more than the sum at stake. For most UK traders, then, the practical protection is IC’s own goodwill and reputation. Our guide to Ombudsman complaints about CFD firms shows the UK process in full.
Sizing your balance around the gap
None of this means IC will fail or treat you unfairly. It means that if either happens, you carry the loss. A sensible response is to keep only working margin at IC and hold everything else at a UK bank or an FCA-authorised firm:
- Deposit what the strategy needs, plus a modest buffer, rather than your whole trading pot.
- Withdraw profits regularly so gains don’t build up offshore. Card withdrawals are capped at what you deposited on that card; the rest goes by wire, which can take up to 14 days.
- Keep records yourself: statements, trade history, the client agreement you signed and every complaint email.
- Cap your own leverage well below the 1:5000 available, since there is no negative balance guarantee.
FX Recap earns affiliate revenue from IC Markets, and our view is the same as elsewhere in this section. An experienced trader who values IC’s raw pricing or cTrader, understands that no UK scheme stands behind the account and keeps only risk capital there can make that choice knowingly. Anyone who relies on the FSCS or the Ombudsman, including most beginners, should use an FCA-authorised provider instead. IC Markets alternatives for UK traders compares them.
Mark had £30,000 set aside for trading and liked IC’s cTrader pricing. After reading the FCA warning and IC’s insurance page, he split the money. He kept £4,000 at IC, enough margin for his usual size on EUR/USD at modest leverage, and put £26,000 with an FCA-authorised spread betting firm, where FSCS cover of up to £85,000 and the Ombudsman applied. Each month he withdrew any profit above £4,000 from IC back to his debit card, up to the amount he had deposited on it. When a £400 slippage dispute arose at IC, he raised it in writing, saved the reply and accepted a partial goodwill credit, knowing there was no Ombudsman to escalate to.
Frequently asked
Is IC Markets covered by the FSCS?
Not for UK residents. The FSCS only protects customers of FCA-authorised firms, and no IC company is authorised in the UK. IC Markets Global’s own entry on the FCA Warning List states that UK customers won’t be protected by the FSCS if the firm fails.
Can I complain to the Financial Ombudsman about IC Markets?
No. The Ombudsman cannot take complaints about IC because it has no UK authorisation. Your routes are IC’s internal complaints process, the Seychelles Financial Services Authority and the Seychelles courts, which govern disputes under clause 28 of the Raw Trading Ltd terms.
Is my money at IC Markets protected up to £120,000?
No. £120,000 is the FSCS limit for bank deposits from 1 December 2025. Investment firms are covered up to £85,000, and only if they are FCA authorised. IC isn’t, so neither figure applies to a UK client.
What is IC Markets’ USD 1 million insurance?
A private client money policy that IC says covers the balance and open positions of IC clients of Raw Trading Ltd if that company becomes insolvent. The page states "up to US$1,000,000 for all claimants", does not name the insurer and gives no claims process. It is not a statutory scheme.
Is the IC Markets insurance USD 1 million per client?
IC’s wording, "up to US$1,000,000 for all claimants", reads as a total limit shared between claimants rather than a per-client amount. IC does not clarify this on the page, so ask for the policy terms in writing if you are relying on it.
Does the CySEC Investor Compensation Fund cover UK traders at IC Markets?
No. The ICF covers clients of IC Markets (EU) Ltd, paying the lower of 90% of the claim or EUR 20,000. Because the EU website says its information is not intended for UK residents, UK clients signing up today are with Raw Trading Ltd in the Seychelles instead.
Does the FSCS cover trading losses at any broker?
No. The FSCS covers a shortfall in client money or assets when an FCA-authorised firm fails. Losses on your trades, however large, are never compensated by the scheme, at IC or at a UK broker.
How can I get FSCS and Ombudsman protection for forex trading?
Use an FCA-authorised provider and check its FRN and contact details on the Financial Services Register. Firms such as Pepperstone (FRN 684312), IG (FRN 195355) and CMC Markets (FRN 173730) fall within both schemes for eligible clients.
Related reading
The team behind this guide
Researched, checked and approved by five forex specialists
Every guide is written, fact-checked and edited before it goes live, and updated when the facts change. Spotted an error? Tell us.